Understanding the Hafrashot and Keren Hishtalmut in Israel
Opening your first paycheck in Israel can be a shock to the system. You see the gross salary you negotiated, but the net amount hitting your bank account looks significantly smaller thanks to a list of deductions known as hafrashot. This guide explains exactly where that money goes, focusing on the mandatory pension and the coveted Keren Hishtalmut, ensuring you maximize your Israeli social benefits.
Decoding the Tlush Sachar: Where Does the Money Go
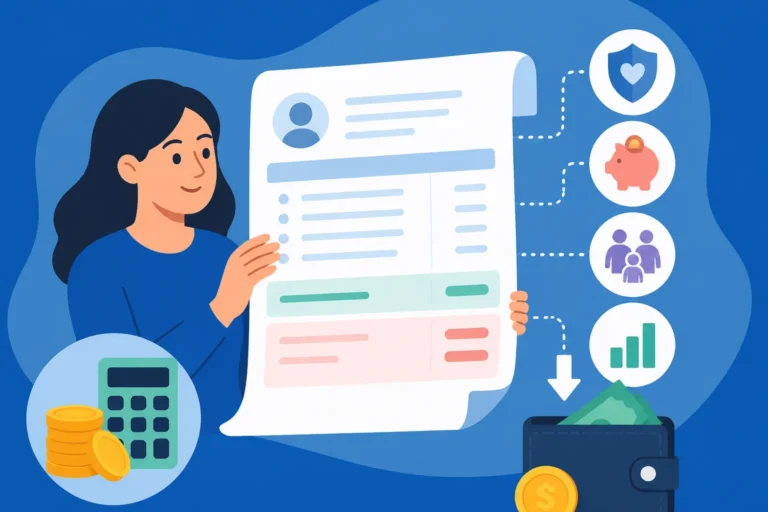
When you sit down at a cafe in Sarona Market and look at your pay stub, the first thing you’ll notice is a column of deductions. In Israel, the Understanding Pay Slips (Tlush Sachar) and Payroll Deductions in Israel is a complex document that reflects a social-democratic history mixed with modern financial regulations. These deductions, or hafrashot, are not just taxes; they are contributions toward your future self. For many expats, the sheer number of line items—Mas Hachnasa, Bituach Leumi, and Pension—can feel like a bureaucratic maze. It is vital to understand that these contributions are split between you and your employer, creating a safety net that is actually quite robust once you know how to navigate it.
The reality of living in Israel is that the "gross" salary is often a misleading figure if you don’t account for these social benefits. While the deductions look high, the employer's side of the hafrashot adds significantly to your total compensation package. This is why veteran expats always negotiate not just the base salary, but the specific terms of their benefits. If you are coming from a country with a different tax structure, you might initially feel frustrated, but these funds are some of the most tax-efficient ways to build wealth in the Middle East.
The Mandatory Pension (Pension Chova)
Since 2008, pension contributions have been mandatory for every employee in Israel. This isn't an optional "opt-in" situation like a 401k; it is a legal requirement. The contribution is typically divided into three parts: the employee’s share (6%), the employer’s share (6.5%), and the employer’s contribution to a severance fund (usually 6% to 8.33%). Understanding how these Understanding Pension and Provident Fund Contributions in Israel work is the cornerstone of your financial life here. For many newcomers, seeing that 6% disappear every month feels like a sting, but remember that your employer is putting in more than double that amount on your behalf.
The pension fund is not just a savings account; it also includes disability insurance and survivors' insurance. This means if you are unable to work due to illness or injury, the fund provides a monthly stipend. For expats, this is a critical layer of protection. However, the paperwork for these funds is almost always in Hebrew. If you are struggling to translate your policy documents, using a service like iTalki to find a Hebrew tutor who specializes in "Business Hebrew" can be a lifesaver. Being able to read the difference between "accumulated savings" and "management fees" is essential for long-term planning.
Severance Pay (Pitzuim)
The "Pitzuim" or severance component of your hafrashot is a uniquely Israeli concept. Most employers contribute 6% of your salary into a dedicated severance fund within your pension. If you are fired or if you resign under certain conditions, you are entitled to this money. Many modern contracts include "Section 14," which stipulates that the money in this fund belongs to the employee regardless of how the employment ends. This effectively acts as a "bonus" or a transition fund if you decide to leave your job. Understanding Severance Pay (Pitzuim) Under Israeli Law is vital because it protects you during the inevitable transitions of the Israeli "startup nation" lifestyle.
There is a frequent misconception among foreigners that you can only access this money when you are old. In reality, the pitzuim can often be withdrawn upon leaving a job, though doing so can significantly reduce your eventual monthly pension payments. It is also important to note that severance pay is subject to specific tax rules. If your payout exceeds the tax-exempt threshold, you could see a large portion taken by the authorities. Consulting with a specialist can help you decide whether to "sequence" your severance or leave it to grow tax-deferred within the pension fund.
National Insurance and Health Tax
Beyond the pension, you will see deductions for Bituach Leumi (National Insurance) and Mas Briut (Health Tax). These are mandatory for almost everyone residing in Israel. These funds pay for your access to the public healthcare system and provide for unemployment benefits, maternity leave, and child allowances. Understanding National Insurance (Bituach Leumi) Contributions in Israel is non-negotiable, as falling behind on these payments can lead to frozen bank accounts and massive fines. For the self-employed, this is even more critical, as you must proactively report your income and pay these dues yourself.
The health tax portion ensures you are covered by one of the four health funds (Kupot Holim). Whether you are in Tel Aviv or a small yishuv in the Galilee, this deduction gives you the right to see doctors, get prescriptions, and access hospital care. While it might feel like another "tax," the cost-to-benefit ratio of Israeli healthcare is generally much higher than in the US or UK. It is worth noting that for high earners, these contributions are capped, which provides some relief on the tlush sachar.
The Keren Hishtalmut: Israel’s Best Financial Secret
If there is one term you must learn in your first week of work, it is Keren Hishtalmut. Originally designed as a "study fund" to allow professionals to take a sabbatical every few years, it has evolved into the most tax-efficient savings vehicle in the country. It is essentially a medium-term savings account where both you and your employer deposit money monthly. The beauty of the Keren Hishtalmut is that after six years, the entire sum—including all the capital gains earned in the market—can be withdrawn completely tax-free.
Unlike the pension, a Keren Hishtalmut is not mandatory by law. It is a "benefit" that is negotiated as part of your contract. However, in sectors like high-tech, engineering, and law, it is a standard expectation. If an employer tells you they don't offer it, you should realize you are effectively taking a 7.5% pay cut compared to the market standard. This fund is one of the primary ways Israelis save for large expenses like a down payment on an apartment or a new car.
How It Works: Contributions and Cycles
The standard contribution structure for a Keren Hishtalmut is 2.5% from the employee and 7.5% from the employer. This means for every shekel you put in, your employer puts in three. This is an immediate 300% return on your investment before the money even hits the stock market. Most employers cap the tax-exempt contribution at a certain salary ceiling (the "ceiling" changes annually), so if you earn a very high salary, you and your employer might only contribute up to that limit to avoid paying unnecessary income tax on the deposits.
The fund operates on a six-year cycle. During the first six years, the money is "locked." You can see it growing in your online portal, but you cannot touch it without paying a massive tax penalty (usually around 35%). However, once the fund reaches its sixth "birthday," it becomes "liquid" (nazil). At this point, you can withdraw the whole amount, or better yet, leave it there to continue growing tax-free for another decade. The flexibility of this fund is what makes it the "holy grail" of Israeli finance.
The Magic of Tax-Free Savings
To understand why everyone is obsessed with their Keren Hishtalmut, you have to look at the Understanding Income Tax Brackets (Madregot Mas) in Israel. Most investments in Israel are subject to a 25% capital gains tax. If you buy a stock and it goes up, the government takes a quarter of your profit. With a Keren Hishtalmut, that 25% stays in your pocket. Over twenty or thirty years, the compounding effect of not paying capital gains tax is worth hundreds of thousands of shekels.
For expats, this presents a unique opportunity but also a potential complication. If you are a US citizen, for example, the IRS does not recognize the tax-free status of the Keren Hishtalmut. This is where a service like Taxes for Expats becomes invaluable. They can help you navigate the complex reporting requirements (like FBAR and FATCA) to ensure you aren't accidentally committing tax evasion in your home country while trying to save in Israel. You need to ensure your Israeli benefits are reported correctly to avoid double taxation issues that can haunt you years later.
Withdrawal Rules and the 6-Year Mark
When your fund finally becomes liquid after six years, you have a big decision to make. Many people use the money for a specific goal, like a wedding or a home renovation. However, seasoned financial planners in Israel often suggest never touching the Keren Hishtalmut if you can avoid it. Because it is the only place you can invest in the S&P 500 or other global indices without paying capital gains tax, it is often smarter to use "taxable" money for your expenses and let the Keren Hishtalmut continue to compound.
If you do need to withdraw the money for educational purposes (its original intent), you can sometimes access the funds after only three years. However, this requires proof of enrollment in a recognized course or degree program. For most expats, waiting the full six years is the standard path. If you are planning on Learning Hebrew: A Complete Guide to Ulpan and Language Levels, you might be able to use the "study" loophole, but generally, it’s easier to just wait. Once the fund is liquid, you can also take out low-interest loans against the balance, which is a common "hack" Israelis use to get cash without actually liquidating their tax-free investment.
Managing Your Funds: Choosing a Provider and Tracking Performance
In Israel, you have the legal right to choose which company manages your pension and your Keren Hishtalmut. Your employer might have a "default" provider, often one of the big insurance giants like Harel, Migdal, Phoenix, or Clalit, but you are not obligated to use them. This is a crucial point of empowerment for foreigners. Many expats find that the default funds have high management fees (dmei nihul) and mediocre investment tracks. Taking control of your funds can mean the difference between a comfortable retirement and a struggling one.
The Israeli financial market is quite concentrated, but there is significant competition between the "traditional" insurance companies and the "investment houses" (batei ha'shkaot) like Altshuler Shaham or Meitav Dash. The investment houses often offer more aggressive, stock-heavy tracks that are better suited for younger workers with a long time horizon. When you move to Israel, don't just sign the papers your HR manager gives you; take the time to research who is actually managing your money.
Selecting a Fund Manager (Menahal Keren)
Choosing a manager involves looking at three things: historical performance, management fees, and customer service. While past performance doesn't guarantee future results, some managers have consistently outperformed the market for over a decade. You can use a government-sanctioned website called "GemelNet" to compare every fund in Israel side-by-side. It is entirely in Hebrew, so again, this is where your efforts in Learning Hebrew: A Complete Guide to Ulpan and Language Levels will pay off.
For many expats, customer service is the biggest hurdle. Some of the older insurance companies have notoriously bad digital interfaces and long wait times on the phone. Newer investment houses tend to have better apps and more English-speaking support. If you are an "Osek Patur" or "Osek Murshe," managing your own contributions becomes even more critical. You should look into How to Get an Israeli Tax File Number for Freelancing to ensure your self-employed contributions are being tracked correctly by the tax authorities.
Investment Tracks: S&P 500 vs. Halachic vs. Bond-Heavy
Once you choose a manager, you have to choose a "maslul" or investment track. By default, most people are put into a "lifecycle" track, which automatically shifts from stocks to bonds as you get older. However, many expats prefer to be more hands-on. In recent years, "Passive S&P 500" tracks have become incredibly popular in Israel because they offer low fees and exposure to the US market. There are also "Halachic" tracks for those who want their investments to follow Jewish law, and "Religious-Sharia" tracks as well.
The difference in returns between a bond-heavy track and a stock-heavy track over 30 years can be millions of shekels. If you are in your 20s or 30s, being in a conservative "general" track might be a mistake. Most Israeli funds allow you to switch tracks online with a few clicks. If you are unsure which track to choose, finding a licensed "Sochen Bituach" (insurance agent) who speaks English can help you align your Israeli hafrashot with your global investment strategy.
Negotiating Management Fees (Dmei Nihul)
This is the most "Israeli" part of the process: everything is negotiable. Management fees are taken in two ways: a percentage of your monthly deposit (dmei nihul mehapkadot) and a percentage of your total accumulated balance (dmei nihul mehatzbiya). The legal maximums are quite high, but almost no one actually pays them. If you are part of a large company, your HR department has likely negotiated "group rates" that are very low.
If you are an individual or work for a small startup, you must negotiate these yourself. A difference of 0.2% in annual fees might seem tiny, but over a lifetime of work, it can eat up 15-20% of your total savings. You can literally call your fund manager and say, "I saw that another company is offering 0.3% on the balance, can you match it?" More often than not, they will. If you find the Hebrew too daunting for this kind of "shuk-style" negotiation, your iTalki tutor can help you role-play the conversation.
Tax Implications and Professional Support for Expats
Navigating the Israeli tax system as a foreigner is like playing chess on a board that is constantly moving. The Complete Guide to Taxes in Israel for Olim and Expats (2027) is filled with nuances, especially regarding the 10-year tax holiday for new immigrants (Olim Chadashim). While your salary is taxed in Israel, your social benefits often fall into a "grey area" of international tax law. This is particularly true for the Keren Hishtalmut and the pitzuim (severance) fund.
If you are working remotely for a foreign company while living in Israel, the situation becomes even more complex. You are likely acting as a freelancer, which means you are responsible for your own hafrashot. In this case, understanding the Self-Employment in Israel: The Osek Patur and Osek Murshe Guide is mandatory to ensure you are setting aside the correct percentages for pension and Bituach Leumi. Failing to do so can lead to a massive tax bill at the end of the year.
Reporting Foreign Income and Double Taxation
For many expats, the biggest fear is paying tax twice on the same shekel. Israel has tax treaties with dozens of countries, including the US, UK, Canada, and most of Europe, to prevent this. However, these treaties don't always cover "social contributions" in a straightforward way. Your Israeli pension might be considered a "Foreign Deferred Compensation Plan" by your home country, which requires specific forms and disclosures.
This is where specialized help is non-negotiable. Using a firm like Taxes for Expats ensures that your Israeli hafrashot are disclosed properly on your home-country tax returns. They understand the specific interaction between the Israeli "tlush" and foreign tax codes. For example, Americans need to be very careful with "PFICs" (Passive Foreign Investment Companies), which can include certain Israeli mutual funds or pension tracks. Getting this wrong can lead to penalties that far outweigh any tax savings you made in Israel.
Understanding the Nekudot Zikui (Tax Credit Points)
In Israel, your income tax is reduced by "Nekudot Zikui" or tax credit points. Every resident starts with 2.25 points, and you get extra points for being an Oleh Chadash, having children, finishing a degree in Israel, or even for being a discharged soldier. Each point is worth a specific amount of money off your monthly tax bill. For a new immigrant, these points can mean paying almost zero income tax on an Understanding Minimum Wage (Sachar Minimum) and Average Salary in Israel for the first few years.
It is vital to check your tlush sachar every month to ensure your points are being applied correctly. Sometimes HR forgets to update your status after you have a child or if you’ve recently finished your "absorption" period. If you see your net salary suddenly drop, the first thing to check is your "Nekudot" balance. If you are unsure how to calculate these, there are many online calculators, but they are mostly in Hebrew, making language skills a prerequisite for financial self-defense.
Language Barriers in Financial Paperwork
Let’s be honest: Israeli financial terminology is brutal. Even Israelis struggle with terms like "Kupa Merkazit L'Pitzuim" or "Sikum Tkufa." For an expat, receiving an 80-page annual pension report in Hebrew can be overwhelming. Many people simply stick it in a drawer and hope for the best. This is a dangerous strategy. You need to know if your employer actually deposited the money they deducted from your check.
To bridge this gap, many expats use a combination of tools. Google Lens can translate snippets of text, but for deep understanding, you need a human. Finding a language partner or a professional coach through iTalki who can walk you through your own documents is one of the best investments you can make. Once you learn the "keywords"—like Hafkado (deposits), Tsua (yield), and Dmei Nihul (fees)—the documents become much less intimidating.
Comparing Benefits: Why These Funds Matter for Your Future
To help you visualize the difference between these two main funds, the table below breaks down the key characteristics of the Pension and the Keren Hishtalmut. Both are essential, but they serve very different roles in your financial life in Israel.
| Feature | Mandatory Pension | Keren Hishtalmut |
|---|---|---|
| Requirement | Mandatory by law for all employees | Optional benefit (negotiated) |
| Employee Contribution | 6% of gross salary | Usually 2.5% |
| Employer Contribution | 6.5% (Pension) + 6% (Severance) | Usually 7.5% |
| Tax Status (Deposits) | Tax-deductible (within limits) | Tax-exempt (up to ceiling) |
| Tax Status (Gains) | Tax-deferred until retirement | 100% Tax-Free after 6 years |
| Liquidity | Locked until age 60-67 | Liquid after 6 years |
| Insurance Components | Includes disability/survivors' insurance | Savings only |
| Best For | Long-term retirement security | Mid-term wealth building / Large costs |
As you can see, the Keren Hishtalmut is a "pure" investment play, while the pension is a comprehensive social security tool. If you are an expat who only plans to stay in Israel for 5-10 years, the Keren Hishtalmut is arguably more important because you will likely be able to take the full amount with you when you leave, whereas the pension is much harder to "move" or liquidate early.
Practical Steps: How to Ensure Your Hafrashot Are Correct
Don't assume that because a company is large or "reputable," your benefits are being handled perfectly. Mistakes happen, and in the "balagan" of Israeli bureaucracy, those mistakes can go unnoticed for years. Every quarter, your pension and Keren Hishtalmut providers will send you a summary. You must match these summaries against your monthly pay stubs.
Specifically, look at the dates. Sometimes there is a lag between the deduction from your salary and the deposit into the fund. If the money isn't in the fund, it isn't earning interest. Over a year, a two-month delay in deposits can cost you significant growth. This is especially important for those in the high-tech sector where salaries are high and the compounding effect is massive.
Reading Your Annual Statements
Once a year, usually around March or April, you will receive a "Duch Shnati" (Annual Report). This is the definitive record of your savings. It will show you exactly how much your fund grew, how much was taken in fees, and what your projected monthly pension will be when you retire. For expats, this report is also the primary document you will need if you ever decide to How to Transfer Your Professional Qualifications to Israel or move your financial life back to your home country.
If you see a section titled "Irregularities" or "Missing Payments," you must address it immediately with your HR department. In Israel, failing to pay into an employee's pension is a criminal offense, so employers are usually very quick to fix errors once they are pointed out. However, they won't point them out to you; you have to find them yourself.
The Role of the Insurance Agent (Sochen Bituach)
Most companies in Israel work with an external insurance agency that handles the hafrashot for all employees. This agent is supposed to be your advocate. When you join a company, you will have a "clita" (absorption) meeting with an agent. They will ask you about your marital status, your health, and your investment preferences.
Do not treat this meeting as a formality. This is your chance to ask: "Are my fees as low as they can be?" and "Is my Keren Hishtalmut in a high-growth track?" If the agent doesn't speak English well, ask for a different agent or bring a friend who can translate. Remember, the agent works for you (and the company), but their commission often comes from the fees you pay, so always be a skeptical consumer.
Disclaimer
This guide is for informational purposes only and does not constitute financial, legal, or tax advice. Israeli regulations and tax laws change frequently. Always consult with a licensed Israeli financial advisor and a qualified tax professional who understands the laws of both Israel and your home country before making significant financial decisions.