What Is the Process for Getting Surgery Covered by My Kupah?
The moment a doctor looks at you and mentions the word "surgery," your mind likely races toward two things: your health and your wallet. In Israel, navigating the healthcare system can feel like trying to solve a Rubik's cube while someone shouts at you in Hebrew. Whether it’s a routine gallbladder removal or a complex orthopedic procedure, understanding the administrative dance required to get your health fund—your Kupah—to foot the bill is essential for your peace of mind and financial stability. This guide walks you through the exact process of securing coverage, from the first referral to the final hospital discharge.
Understanding the Foundation: The Health Basket and Your Kupah
The Israeli healthcare system is built on the principle of universal coverage, but that doesn't mean everything is automatic. Every citizen and permanent resident is entitled to a "Health Basket," known as the Sal Briut, which is a list of medical services, medications, and treatments that the state must provide. When you are looking for surgery, the first question the system asks is whether the procedure is included in this basket. If it is, the path to coverage is relatively straightforward, provided you follow the rules of your specific Kupat Holim—be it Clalit, Maccabi, Meuhedet, or Leumit.
For those who are still in the early stages of their move, How Long Until New Olim Get Health Coverage in Israel? is a crucial read, as there is often a gap between arriving and being fully integrated into the National Health Insurance system. During these "waiting periods" or for those on specific visas who haven't yet qualified for a Kupah, a bridge solution like SafetyWing can be a lifesaver, providing international medical coverage before the local system kicks in. SafetyWing is particularly popular among digital nomads and those in the process of transitioning their residency status because it handles the unexpected when you are technically "between" systems.
The Sal Briut is updated annually by a committee that weighs the cost-benefit of new technologies. You can find out more about this by reading Understanding the Health Basket (Sal Briut) and What It Covers. If your surgery is in the basket, your Kupah is legally obligated to provide it, but they get to decide where and by whom if you are using the basic level of coverage. This is where the tension often lies for expats who are used to more individual choice in their medical care.
The Step-by-Step Pathway to Surgery Coverage
Getting your surgery covered is a linear process, but it requires you to be proactive. You cannot simply walk into a hospital and expect the Kupah to pay later. Everything hinges on prior authorization and a very specific set of documents that serve as the currency of the Israeli medical world.
The Initial Referral (Hafnaya)
Everything starts with a referral, or a Hafnaya. You cannot self-refer to a surgeon. Your journey begins in the office of your primary care physician. If you haven't yet established a relationship with one, you should look into How to Choose a Family Doctor (Rofeh Mishpacha) in Israel to find someone who understands your medical history. The family doctor will evaluate your symptoms and, if necessary, issue a digital referral to a specialist.
Once you have that referral, you must see a specialist within your Kupah’s network. For example, if you are with Maccabi, you need to see a Maccabi-affiliated surgeon. They will perform the final diagnostic workup and decide if surgery is the appropriate course of action. For a detailed breakdown of this specific step, see How to Get a Referral (Hafnaya) to a Specialist in Israel. This specialist will then issue a formal recommendation for surgery, which includes the specific medical codes for the procedure.
Obtaining the Tofes 17 (Commitment Letter)
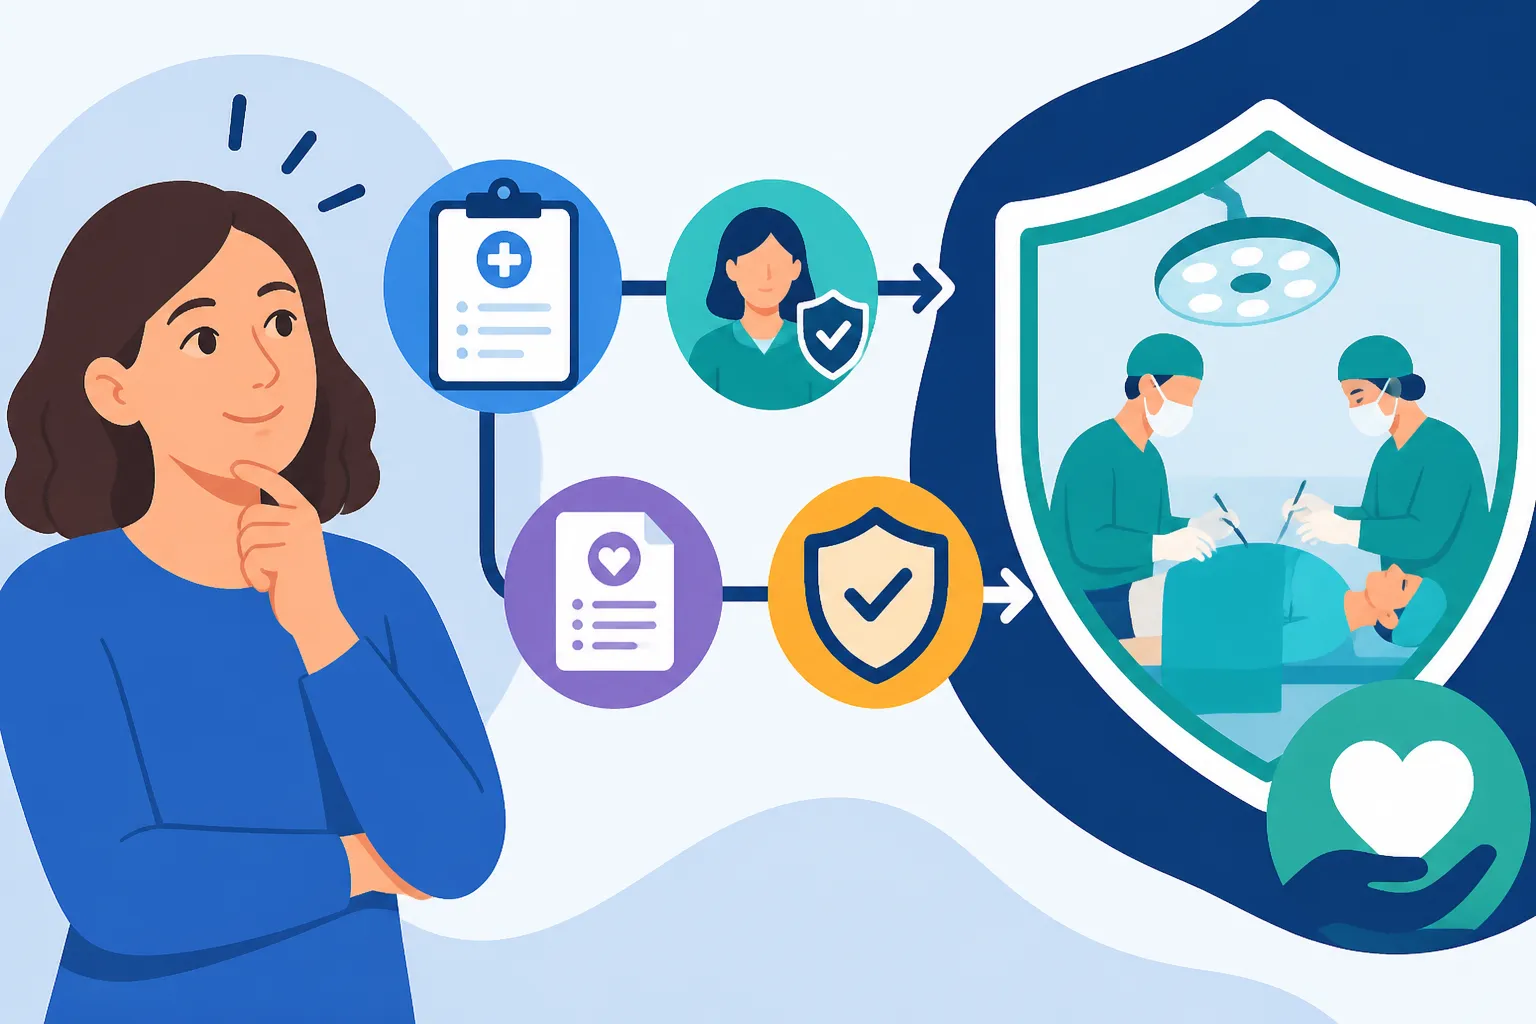
This is the most critical part of the process. In Israel, the Tofes 17 (officially called a Hitchayvut) is a commitment letter from your Kupah to the hospital, promising to pay for the procedure. Without this document, the hospital will either ask you for a credit card deposit or refuse to admit you for a non-emergency procedure. To get a Tofes 17, you usually need to upload the surgeon's recommendation and the hospital's invitation to the Kupah’s app or website.
Navigating the digital portals can be daunting if your Hebrew is shaky, but tools like How to Book Appointments Through Clalit and Maccabi Apps provide some guidance on using these systems. Once the Kupah reviews the request, they will issue the Tofes 17. Be aware that the Kupah might try to direct you to a specific hospital where they have a cheaper contract. If you have a strong preference for a facility like Ichilov in Tel Aviv or Sheba Tel HaShomer, you may need to advocate for yourself or rely on your supplementary insurance.
The Role of Supplementary Insurance
Most expats opt for the higher tiers of insurance, such as Clalit Platinum or Maccabi Sheli. These plans are vital when you want more control over the "where" and "who" of your surgery. If you are wondering if the extra monthly cost is worth it, check out Is Bituach Mashlim Worth It for Expats in Israel?. These supplementary plans often allow you to choose a private surgeon and have the surgery performed at private facilities like Assuta or the Herzliya Medical Center, with the Kupah covering a significant portion of the cost.
For those who are not yet eligible for these high-tier local plans, SafetyWing offers a different kind of security, especially for those who travel frequently or are still navigating the bureaucracy of Bituach Leumi. SafetyWing can provide a global safety net that ensures you aren't left entirely out of pocket if a medical necessity arises while your local Israeli coverage is still being processed.
Public vs. Private: Navigating Choices and Waiting Lists
One of the biggest culture shocks for foreigners in Israel is the realization that the public system, while medically excellent, often comes with significant waiting times. If you go through the standard public route, you may wait months for a non-urgent surgery. Furthermore, you generally do not get to pick your specific surgeon; you get whoever is on duty that day.
| Feature | Public Path (Standard Sal Briut) | Private Path (Supplementary/Mashlim) |
|---|---|---|
| Surgeon Choice | Assigned by the hospital department | You choose from a list of specialists |
| Facility | Public hospitals (e.g., Rambam, Soroka) | Private hospitals (e.g., Assuta, HMC) |
| Waiting Time | Can be several months for elective cases | Usually much faster (weeks) |
| Out-of-Pocket Cost | Minimum co-pays (Tofes 17 fee) | Higher co-pays for surgeon/facility |
| Luxury Level | Shared rooms, standard amenities | Private/semi-private rooms, higher service |
Choosing between these paths is a personal decision based on your urgency and budget. We delve deeper into this comparison in Public vs Private Healthcare in Israel: Which Should Expats Choose?. In Jerusalem, for example, many choose the "Sharap" system at Hadassah, which allows for private medical services within a public hospital setting. You can learn more about how this unique hybrid works in What Is Sharap and How Do Private Services Work in Israeli Hospitals?.
If you find the waiting lists in the public system too long, your supplementary insurance is your best friend. It bridges the gap by allowing you to "jump the queue" by going private, though you will still need to manage the Understanding Co-Payments (Hishtatfut Atzmit) in the Israeli Health System that come with these premium options.
Logistics, Costs, and Pre-Op Essentials
Even with a Tofes 17 in hand, there are logistical hurdles to clear. The hospital will require a battery of pre-operative tests, often including blood work, an EKG, and sometimes a chest X-ray. These tests should also be done through your Kupah to ensure they are covered. If you try to do them privately at the last minute, you will likely face high costs.
Managing Co-Payments and Fees
While the bulk of the surgery cost is covered by the Kupah, you will almost always have a small administrative fee for the Tofes 17 itself, usually around 30 to 40 Shekels. If you are going the private route via your supplementary insurance, the co-payment for the surgeon can range from a few hundred to several thousand Shekels, depending on the complexity of the operation and the seniority of the doctor. It is always wise to ask for a "price quote" (Haza'at Mechir) from both the surgeon and the hospital before committing.
Choosing the Right Health Fund
Your experience with surgery coverage can vary slightly depending on which Kupah you belong to. Some are known for having better "arrangements" with certain private hospitals, while others have more robust internal surgical departments. When you are first settling in, Choosing a Kupat Holim in Israel: Clalit, Maccabi, Meuhedet or Leumit (2027) is a great resource to help you decide which fund aligns with your specific health needs and geographic location.
Handling Emergencies and Travel
If your surgery is the result of an emergency, the process is different. You should head straight to the nearest emergency room. To understand the costs and protocols of emergency visits, read Emergency Medical Care in Israel: What Every Newcomer Needs to Know. If you happen to be traveling outside of Israel when a medical issue arises, local Kupah coverage is generally not applicable. This is another area where SafetyWing excels, offering travel medical insurance that covers you globally, which is a necessary addition to any local Israeli plan for those who don't spend 365 days a year within the borders.
Finally, ensure you have all your medical records translated or at least summarized in English or Hebrew. While many Israeli doctors speak excellent English, the administrative staff processing your Tofes 17 might not. Having a clear, concise summary of why the surgery is necessary can speed up the approval process significantly and help you avoid the dreaded "request for more information" that can delay your procedure by weeks.
Disclaimer
This guide is intended for informational purposes only and does not constitute legal or medical advice. The Israeli healthcare system and the policies of individual Kupot Holim are subject to frequent change. Always consult directly with your health fund provider and a qualified medical professional regarding your specific situation and coverage eligibility.